
Credit card rewards are an appealing feature for many cardholders in New Zealand. They can turn everyday spending into points, cashback, or travel benefits. This guide explains how reward programmes work, the main reward types available, how to compare options, common pitfalls and practical steps consumers may want to consider when choosing and using a rewards card. The aim is to provide clear, general information rather than personal advice.
What are credit card rewards?
Credit card rewards are incentives offered by card issuers to encourage spending on a card. Rewards typically come in the form of points in a loyalty programme, cashback credited to the card account, frequent flyer or travel credits, retail discounts, or a combination of these. Rewards are designed to provide value back to cardholders based on their spending patterns.
How rewards programmes are structured
Most reward programmes operate on an earn and redeem model. Cardholders earn rewards as they use the card, usually at a fixed rate or within specified categories. Redeeming rewards may be possible for flight redemptions, statement credits, retail vouchers, gift cards, or merchandise. The flexibility and relative value of each redemption option can vary, and programme rules often set minimums, expiry dates, and other conditions.
Common types of credit card rewards
Different cards prioritise different reward styles. Understanding the main types helps when aligning a card with spending habits and financial goals.
Points and loyalty programme rewards
Points are a common reward format. Points accrue based on eligible transactions and can often be redeemed within a loyalty programme for flights, accommodation, retail items or partner services. Some schemes allow points to be transferred to airline or hotel partners, which may increase redemption flexibility. Consumers may want to verify transfer ratios and partner lists before relying on transfers.
Frequent flyer and travel points
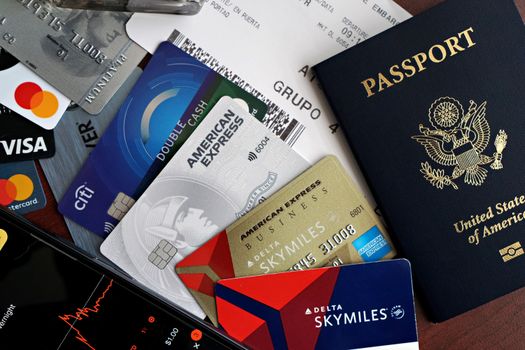
Frequent flyer cards earn airline-linked points or miles that are redeemable for flights, upgrades, lounge access or baggage benefits. These cards can be attractive for regular travellers if the earning rate and airline partnerships match travel patterns. It is useful to consider how easy it is to redeem seats, peak travel restrictions and whether points expire.
Cashback
Cashback returns a percentage of eligible spending to the cardholder, typically as a statement credit or direct account payment. Cashback can be simple to understand and use, but card terms may limit eligible categories or cap cashback earnings. Some cards offer tiered cashback rates for different spending categories.
Retail and partner discounts
Certain cards provide discounts or special offers with partner retailers, including bonus points promotions, discounted membership fees or bonus credit for specific categories. These benefits can be valuable for people who frequently shop at partner outlets, but partnership arrangements change from time to time.
How rewards are earned and calculated
Understanding earning mechanisms helps estimate potential value. Key variables include the earning rate, eligible transaction types, exclusions and bonus categories.
Earning rates and eligible spend
Earning rates are often expressed as points per dollar or as a percentage cashback. Some cards offer higher earning rates for categories such as groceries, fuel or travel, while lower rates may apply to general spending. Transactions that are often excluded from rewards include cash advances, balance transfers, certain bill payments, fees and interest charges.
Bonus earn and introductory offers
Issuers may provide introductory bonuses, for example bonus points or elevated cashback after meeting a minimum spend within a set period. These offers can boost short-term returns but consumers may want to read the terms carefully for minimum spend thresholds and expiry of earned bonus rewards.
Redeeming rewards
Redemption options and their relative value differ between programmes. The same number of points may be worth more when used for flights than when redeemed for merchandise, for example.
Redemption routes and value
Common redemption options include flights, gift cards, statement credits and merchandise. Frequent flyer redemptions can offer high value per point when seat availability and partner routing are favourable. Cashback and statement credit options are typically straightforward but may yield lower per-dollar value compared with optimised point redemptions.
Expiry and activity requirements
Many programmes have expiry rules that can reduce long-term value. Points may expire after a set period of inactivity, or programme rules may change. Individuals may want to check expiry terms and ways to keep accounts active, such as regular small purchases, if preserving points is important.
Balancing rewards against costs
Rewards can add value, but they are rarely free. Annual fees, interest charges and other costs can erode or eliminate the net benefit of rewards if they are not managed carefully.
Annual fees
Many reward cards charge an annual fee. Cards with higher rewards or more premium benefits often have higher fees. It may be helpful to estimate the break-even point where rewards earned offset the annual fee, given typical monthly and annual spending. For some consumers, a no-fee or low-fee card with modest rewards may be a better fit.
Interest and revolving balances
Interest charges on revolving card balances usually exceed the value of rewards earned. Carrying a balance can therefore negate rewards. Consumers aiming to benefit from rewards typically consider paying the full statement balance each month to avoid interest that reduces net returns.
Foreign transaction fees and travel costs
If travelling overseas or buying in foreign currencies, foreign transaction fees can reduce the benefit of travel rewards. Some cards waive these fees, but others charge a percentage on foreign transactions. It is useful to factor these costs into overall comparisons.
How to compare rewards cards
Comparing cards requires attention to earning structures, redemption options, fees and practical usability. A considered approach helps align a card with spending habits.
Match rewards to spending patterns
Identify where most spending occurs and prioritise cards that reward those categories. For example, if a large proportion of expenditures is on travel or accommodation, travel-linked rewards may offer higher value. For everyday grocery and fuel spending, category-specific cashback or points may be more relevant.
Consider redemption flexibility and partners
Flexible points that transfer to multiple travel partners can be more useful than points restricted to a single redemption option. The availability of airline or hotel partners, transfer ratios and seasonal availability are practical considerations when aiming to get the most value.
Factor in fees and other benefits
Assess annual fees, foreign transaction fees and additional benefits such as travel insurance, purchase protection or lounge access. Extra benefits can offset some fees, but their usefulness depends on individual circumstances and travel frequency.
Tips for maximising rewards
There are practical steps that may help increase overall value from a rewards card while managing risk and cost.
Use the right card for the right spend
Where possible, allocate spending to the card that offers the best rewards for that category. This may involve using multiple cards to cover different categories, but it is important to keep track of billing dates, payment obligations and any annual fees to ensure net benefit.
Plan around sign-up bonuses
Introductory bonuses can be attractive, however they often require meeting a minimum spend within a specific timeframe. Consumers may want to budget planned purchases to meet these thresholds responsibly rather than increasing spending unnecessarily or using credit to reach a target.
Monitor reward promotions and partner deals
Card issuers and partners frequently run promotions that increase earning rates or offer discounted redemptions. Staying informed about temporary bonus categories or limited-time offers can improve returns, but it may also require regular review of programme communications.
Track points and expiry dates
Keeping an eye on balances and expiry terms helps prevent lost value. Where points are at risk of expiring, small qualifying transactions or other activity may preserve the balance, depending on programme rules.
Common pitfalls to avoid
Cardholders may face several risks when pursuing rewards. Awareness of these pitfalls can reduce the likelihood of unexpected costs.
Paying interest that wipes out rewards
High interest charges on unpaid balances often outweigh rewards earned. If the account is carried in a revolving state, the financial benefit of rewards is likely to be limited or negative.
Overextending to chase rewards
Chasing bonuses or higher-tier reward levels by spending beyond means can lead to financial strain. It is generally prudent to pursue rewards within a budgeted spending plan.
Underestimating restrictions and fees
Rewards programmes may include restrictions on redemptions, blackout dates, fees for redemptions or changes, and minimum redemption thresholds. These limitations can reduce practical value. Reading the terms and conditions helps set realistic expectations.
When rewards may not be worth it
For some consumers, rewards cards are not the best fit. Scenarios where rewards may be less beneficial include low annual spending that does not offset fees, frequent use of credit leading to interest charges, or a preference for simple, no-fee cards that avoid potential complexity.
Where to find more information and comparisons
Comparing options across issuers and reward types can be time consuming. Comparison resources that list current reward structures and broad card features can help with initial research. For general comparisons and to explore rewards categories, consider reputable comparison pages which summarise common reward types and features.
For example, a general overview of rewards options and features may be available at Credit Cards Compare. To review cards focused on reward value, a summary page can be found at Best credit card rewards in NZ. For those specifically interested in travel-related cards and airline partnerships, a dedicated frequent flyer credit card section is typically helpful, for example Frequent flyer credit cards.
Final considerations
Credit card rewards can provide meaningful benefits when aligned with personal spending and travel habits, and when cards are used responsibly. It may be helpful to compare potential rewards against fees and likely interest costs, to read programme terms carefully, and to consider redemption flexibility. Consumers who prefer simplicity may prioritise straightforward cashback or no-fee options, while those who travel frequently may focus on flexible points and airline partnerships.
As reward programmes and card features change over time, staying informed through issuer communications and trusted comparison resources can assist with ongoing decisions. This information is general in nature and not personalised financial advice. For specific financial decisions, obtaining tailored guidance from a qualified adviser may be appropriate.

